 Policyholder Pulse
 Ramaco got the coal moving again in weeks. Its insurers took years to pay. Under West Virginia’s Hayseeds rule, the cost of that wait can give rise to a separate and substantial recovery.
Policyholders and insurers alike should take note.


Ramaco got the coal moving again in weeks. Its insurers took years to pay. Under West Virginia’s Hayseeds rule, the cost of that wait can give rise to a separate and substantial recovery.
Policyholders and insurers alike should take note.
It is nearly five years since the winter storms caused blackouts across Texas, when over four million customers lost power as the ERCOT power grid nearly failed. And while the Texas grid weathered the most recent winter storm, what’s clear is that demand and weather conditions continue to put immense strain on the nation’s electric grid.
 The Illinois Supreme Court has teed up a significant insurance question: Does a standard pollution exclusion bar coverage when the alleged “pollution” was not considered to be pollution when the policy issued—where the substance was lawfully emitted under an environmental permit?
The court accepted a certified question from the Seventh Circuit on April 17, 2025, in Griffith Foods International Inc. v. National Union Fire Insurance Co.—a case that springs from the Sterigenics ethylene-oxide suits. The court’s agreement to consider the question signals the potential for a landmark ruling on the scope of pollution exclusions, with far-reaching implications for companies dealing with environmental and related toxic tort claims.
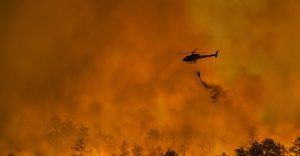 As of January 13, Southern California’s ongoing wildfires have reportedly destroyed more than 12,000 structures. Insured loss estimates exceed $25 billion, and the strong Santa Ana winds fanning the blazes are expected to continue into Wednesday.
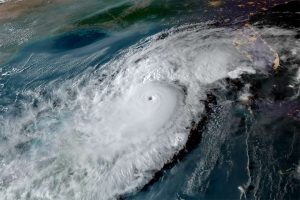 In the aftermath of two powerful hurricanes the process of assessing the damage and rebuilding begins. Businesses suffered billions of dollars in losses during hurricanes Helene and Milton, both in physical property damage and disruption of their business (i.e., lost profits). That is precisely why businesses purchase property and other commercial insurance—to indemnify them when disaster strikes. However, it is not uncommon for businesses to be unpleasantly surprised when they present a claim to discover that their insurers are unwilling to stand behind the full insurance coverage they promised. This is particularly so in the case of a substantial loss, and even more so in the aftermath of a wide-area catastrophe—such as a hurricane or other natural disaster—because such catastrophes have negative repercussions on insurers given the number of impacted policyholders.
This article highlights eight property adjustment and coverage issues. Understanding and being thoughtful about these issues now, including working with coverage counsel as appropriate, is critical to maximizing insurance recovery.
Hurricane Helene struck Florida’s Big Bend region as a category 4 hurricane on September 25, 2024, and continued to move northeast. The storm caused widespread power outages and catastrophic damage across Florida, the Carolinas, Tennessee, Georgia and other states. It has brought life-threatening storm surges in its aftermath. Now, less than two weeks later, Hurricane Milton is making its way toward Florida’s western coast and threatens to cause additional catastrophic damage.
The below checklist includes essential considerations and steps to take for property owners and businesses that stand to be affected by hurricanes.

In a recent win for policyholders, the Supreme Court of Colorado handed down a pair of decisions that extended the notice-prejudice rule to first-party property policies. Colorado law now requires an insurer to demonstrate that it was prejudiced by the insured’s late notice of a claim before it can deny coverage based on untimeliness in both property and liability policies.
 The Illinois Supreme Court handed down a big win for policyholders just in time for the holidays. In Acuity v. M/I Homes of Chicago, LLC, the court joined the mainstream of jurisdictions and reversed years-old precedent that severely limited policyholders’ ability to tap their liability coverage for construction defect and faulty workmanship claims.
 Temperatures in Arizona this week reached over 110 degrees Fahrenheit. The water temperature in the Florida Keys was reported to reach sauna-like levels, threatening the life of habitat-sustaining coral. Atmospheric conditions are routinely blamed for violent storms and for wildfires that darken the skies.