

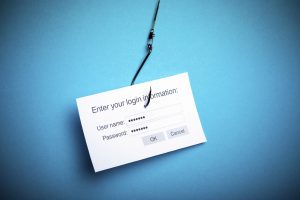
Phishing is a criminal hacker’s favorite sport, and for good reason. It’s a tried and true way to land the big one, over and over again. Whether using a spoofed bank website and stolen email addresses to trick customers into divulging account information, sending email messages purporting to be from a senior company official to deceive employees into providing personal health records, or posing as a trusted vendor and transmitting wire transfer instructions to fraudulently divert funds, hackers are reeling in the catch and making it look easy.
But a well-managed company should have sophisticated safeguards in place. And if these fail, there is insurance coverage, right? The prudent policyholder buys all kinds of insurance: It has up-to-the minute “Cyber” coverage. It has Crime and Fidelity coverage with Computer Fraud riders. It has Professional Liability coverage. And of course it has regular old Commercial General Liability and Property coverage. Surely it’s covered for this type of fraud. Or is it?
While seeming to offer products that respond to the latest risks, insurers often provide limited coverage and seek to exclude the most obvious and inevitable losses. A series of recent cases highlight some of the biggest holes in the insurance safety net.
 A policyholder requests consent to settle with the underlying claimant? Reservation of rights.
 a partially autonomous automatic braking and steering system on the Tesla Model S—one of 70,000 such vehicles now on the roads—the auto industry is roaring ahead with autonomous vehicles (AVs). Google is testing its driverless cars extensively on U.S. roads; General Motors has teamed up with car-sharing company Lyft to develop a driverless taxi service; and
 Thus, it is imperative that contractors have the right pollution coverage in place to remain secure and profitable.
 it prevents the insurer from “pass[ing] the incidence of loss, at least in part, from itself to its own insured and thus avoid[ing] the coverage which the insured purchased.”
 suggest that the courts have recognized that denying claims based on vague concepts of “insurability” creates too much uncertainty for policyholders and have found several ways to curtail this overreaching practice.
 When a jury awards punitive damages against an insurance company for bad faith, the maximum it may award is determined based on a multiple of its underlying award of compensatory damages and attorney fees (so-called “Brandt fees”). In a June 9 decision, the California Supreme Court unanimously held that when a judge, instead of a jury, awards the attorney fees, they should still be included when considering the maximum punitive damages the jury may award.